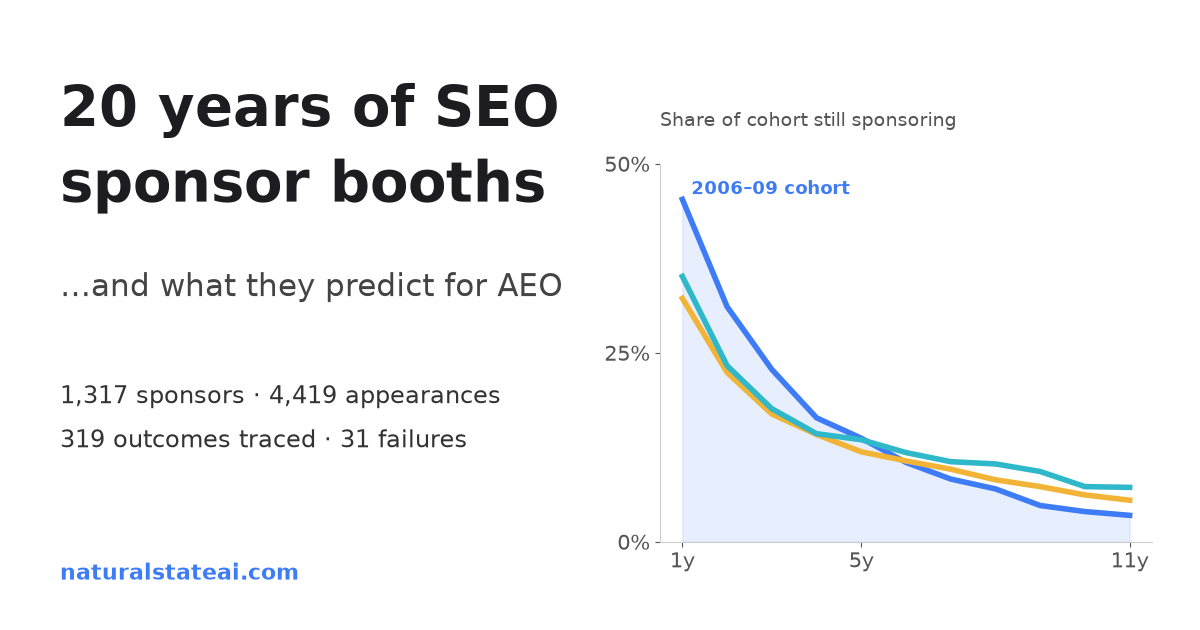
I traced 1,317 companies that sponsored SMX, SES, Pubcon, BrightonSEO, MozCon, SEO Week and SearchLove from 2006 to 2026. The pattern of who consolidated, who died and why is the best map I have for where AI search vendors are headed.
- The expo floor
- What I built
- Five eras of sponsors
- The graveyard
- Patterns, with numbers
- Predictions for AEO
- What to do
- Sponsor explorer
- Methodology and caveats
- Sources
The expo floor
Walking the BrightonSEO expo hall this month, I kept having the same thought: I have seen this booth before. The stands were dominated by two pitches: prompt tracking and AI visibility scores, and link builders who had found a new word, citation building. I wrote about that in my takeaways post: https://www.naturalstateai.com/brightonseo-2026-takeaways/
One conversation made it concrete. I spoke with a former Datorama employee who pointed out that today's sponsors are all different from the last time they came to BrightonSEO with Datorama. Datorama itself went the way most of these vendors go: Salesforce completed its acquisition in August 2018 (https://www.salesforce.com/news/stories/datorama-has-joined-the-salesforce-family/).
The industry moves like a hive. So instead of guessing which AEO vendors will last, I went back through 20 years of sponsor lists to see what happened to the last few hives.
What I built
- Sponsor and exhibitor pages for SMX, SES, Pubcon, BrightonSEO, MozCon, SEO Week, SearchLove, Tech SEO Connect and Ahrefs Evolve, 2006–2026, mostly pulled from Wayback Machine snapshots.
- Every appearance row keeps the archived page it came from; company names were normalized and merged by alias.
- For 319 companies I traced what happened next (acquired, merged, shut down, pivoted, rebranded, independent, public) from press releases, filings and trade press, each with a source link.
- Each traced company has a theme (for example paid-search tools, rank tracking, link building, AI search) and an era based on its first sponsorship year.
- Where a company failed, I recorded the primary cause the source gives, or marked it unknown.
I did not fill gaps with guesses. Where I could not verify an outcome, it says unknown.
Five eras of sponsors
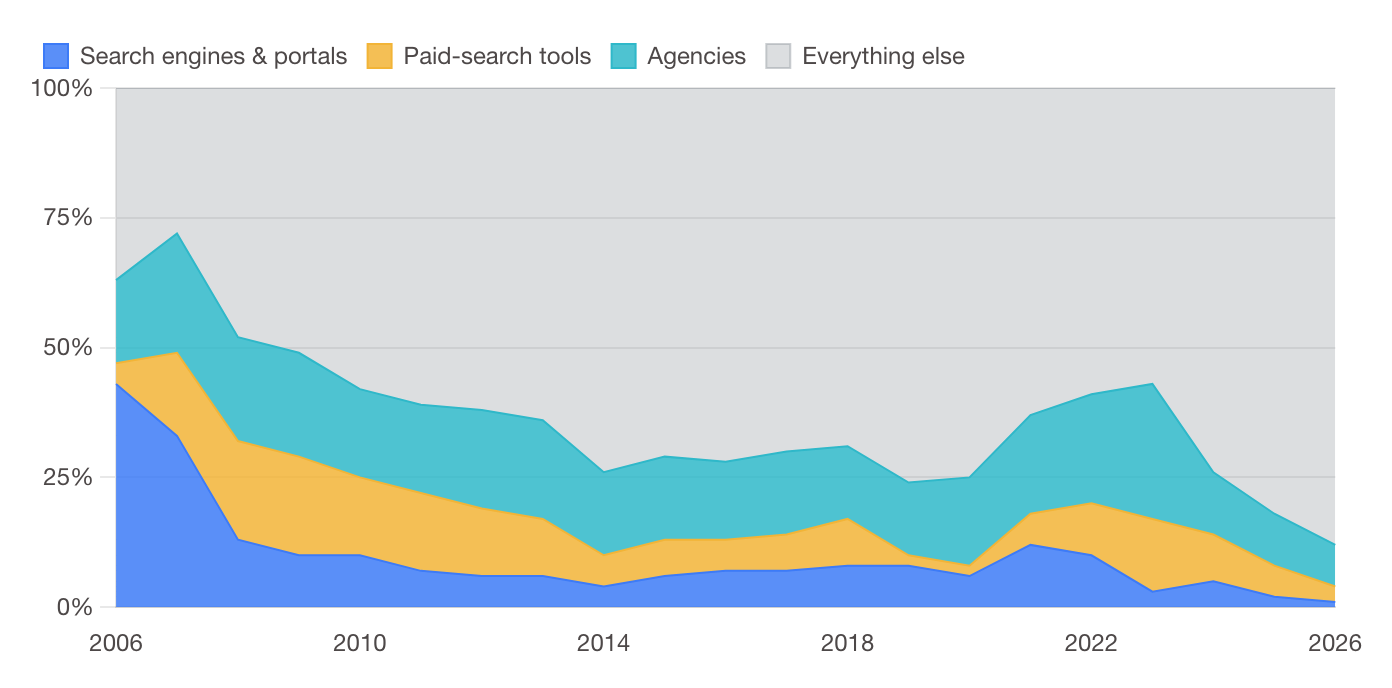
Search engines and portals were 43% of researched sponsor appearances in 2006 and 1% in 2026. Rank tracking and SEO suites went from 4% to 31%. AI search and AEO vendors went from zero before 2022 to 15% in 2026.
| Era | First-time sponsors | Still 2023+ | Traced | Consolidated | Independent | Died |
|---|---|---|---|---|---|---|
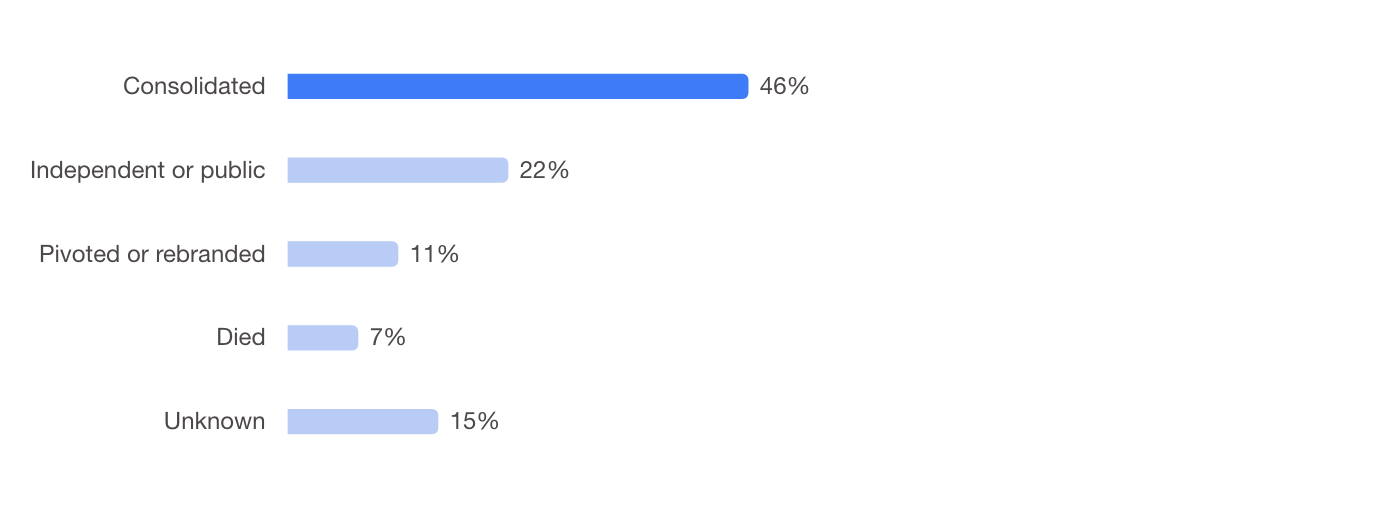
| 2006–09 | 373 | 7 (1.9%) | 133 | 46% | 22% | 7% |
| 2010–14 | 438 | 27 (6.2%) | 100 | 41% | 37% | 9% |
| 2015–19 | 245 | 32 (13%) | 43 | 26% | 67% | 5% |
| 2020–22 | 27 | 10 | 6 | 17% | 83% | 0% |
| 2023–26 | 234 | n/a (current) | 37 | 8% | 92% | 0% |
Every cohort looks healthy for its first five years. The 2023–26 cohort shows 92% independent for the same reason the 2006–09 cohort did in 2010: not enough time has passed.
The graveyard
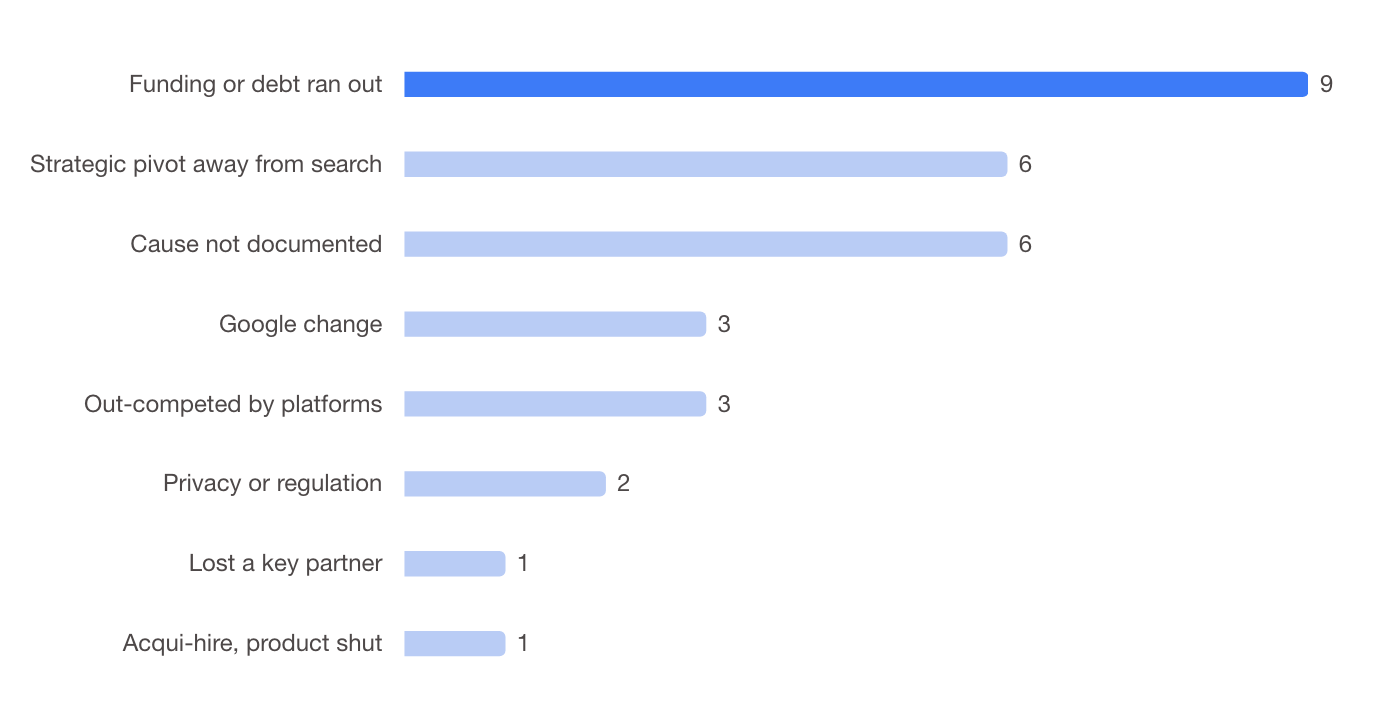
That is 31 failures among 319 traced companies: 20 shutdowns, 8 pivots away from the original business, and 3 distressed exits (Idearc and Superpages through bankruptcy, Become.com squeezed by Google Shopping). Another 114 companies were acquired or merged with no distress documented; I count those as consolidation, not failure.
Money ran out most often, but platforms sit behind more of these stories than the Google row shows. Count Google changes, platform competition, privacy rules and lost partners together and they match the funding failures at 9.
| Company | What they sold | Cause | Timeline | Source |
|---|---|---|---|---|
| Marin Software | Enterprise paid-search bid and campaign management | Out-competed or commoditized by platforms | 2007 first booth, 2013 IPO, revenue down every year from 2016, 2020 last booth, Chapter 11 on July 1 2025 | sfgate.com |
| Local.com | Local search portal and ad network | Google change | 2008 first booth, 2011 last, 2013–14 Google changes, Chapter 11 June 2015, assets sold Dec 2015 | sec.gov |
| Become.com | Comparison-shopping search engine | Google change | 2008 booth, Dec 2014 sold to Connexity (ex-Shopzilla), itself resold by Scripps for $165M in 2011 after a $525M purchase in 2005 | techcrunch.com |
| Jumpshot | Clickstream panel data (Avast subsidiary) | Privacy/regulation | 2015 first booth, 2017 last, shut down Jan 2020 | en.wikipedia.org |
| Klout | Social influence scores | Privacy/regulation | 2011 booths, 2014 acquired, shut down May 25 2018 | techcrunch.com |
| Trada | Crowdsourced PPC management marketplace | Funding or debt ran out | 2010 first booth, 2012 last, 2013 layoffs and restructuring, shut March 2015 | bizwest.com |
| Slingshot SEO | SEO agency services (Indianapolis) | Google change | 2011 first booth, 2012 last, core agency closed 2016, brand sold 2018 | ibj.com |
| Chitika | Search-targeted contextual ad network for publishers | Lost key partner | 2009 booth, shut down April 2019 | ppc.land |
| AdBrite | Self-serve ad exchange | Funding or debt ran out | 2006 booth, shut Feb 1 2013 | techcrunch.com |
| Anchor Intelligence | Click-fraud detection | Funding or debt ran out | 2008 first booth, 2010 last, ceased operations Dec 2010 | techcrunch.com |
| Compete | Clickstream traffic estimates | Out-competed or commoditized by platforms | 2009 first booth, 2011 last, closed Dec 31 2016 | martech.org |
| Optify | SEO and inbound marketing software (Seattle) | Funding or debt ran out | 2010 first booth, 2013 last, shut Nov 2013 | geekwire.com |
| Pricesearcher | UK product price search engine | Funding or debt ran out | 2017 first booth, 2018 last, administration March 2020, dissolved May 2022 | find-and-update.company-information.service.gov.uk |
| Text Link Ads and teliad | Paid-link and advertorial marketplaces | Google change (current status of both not verified) | Their penalty wave created Kerboo (retired 2021) and Remove'em (retired 2025) | searchengineland.com |
Patterns, with numbers
Almost nobody stays on the floor
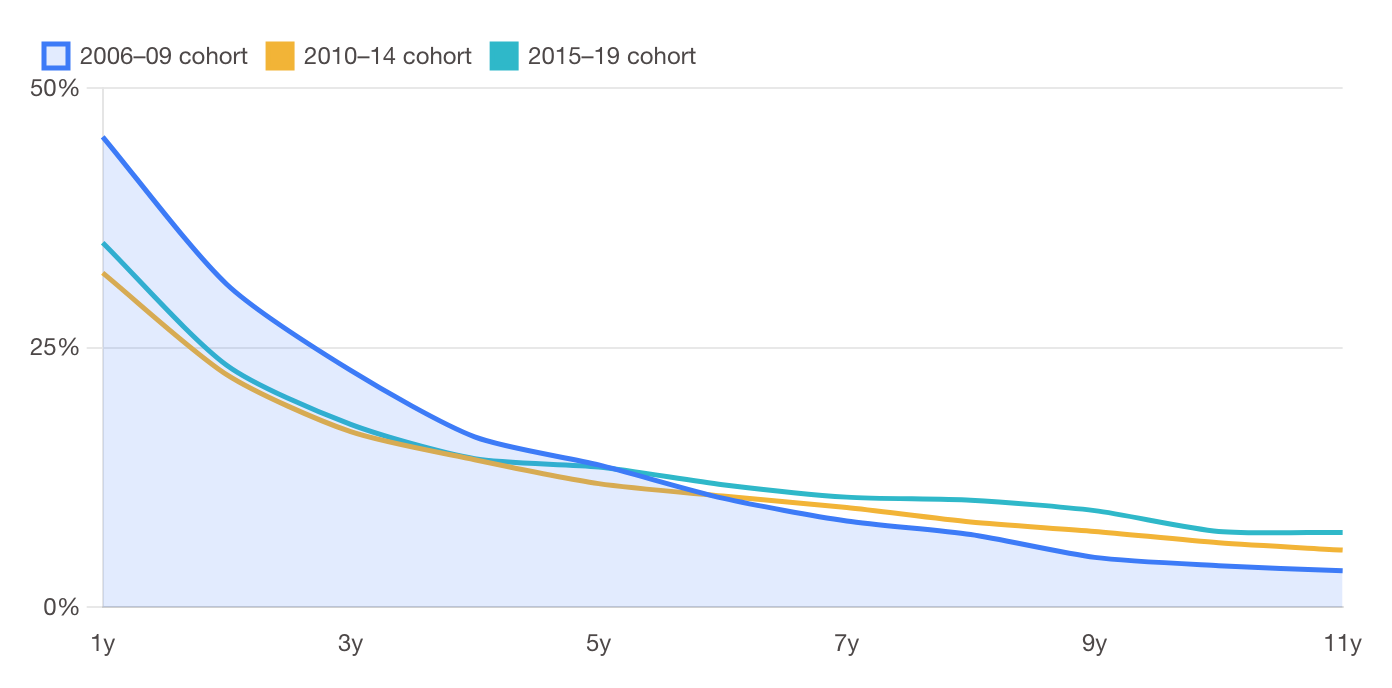
Share of each cohort that sponsored again at least this many years after its first booth. Of 373 companies that first sponsored in 2006–09, 7 were still sponsoring in 2023 or later: Google, Microsoft, Bruce Clay, Moz, Textbroker, SEO Samba and iCrossing.
Outcomes by category
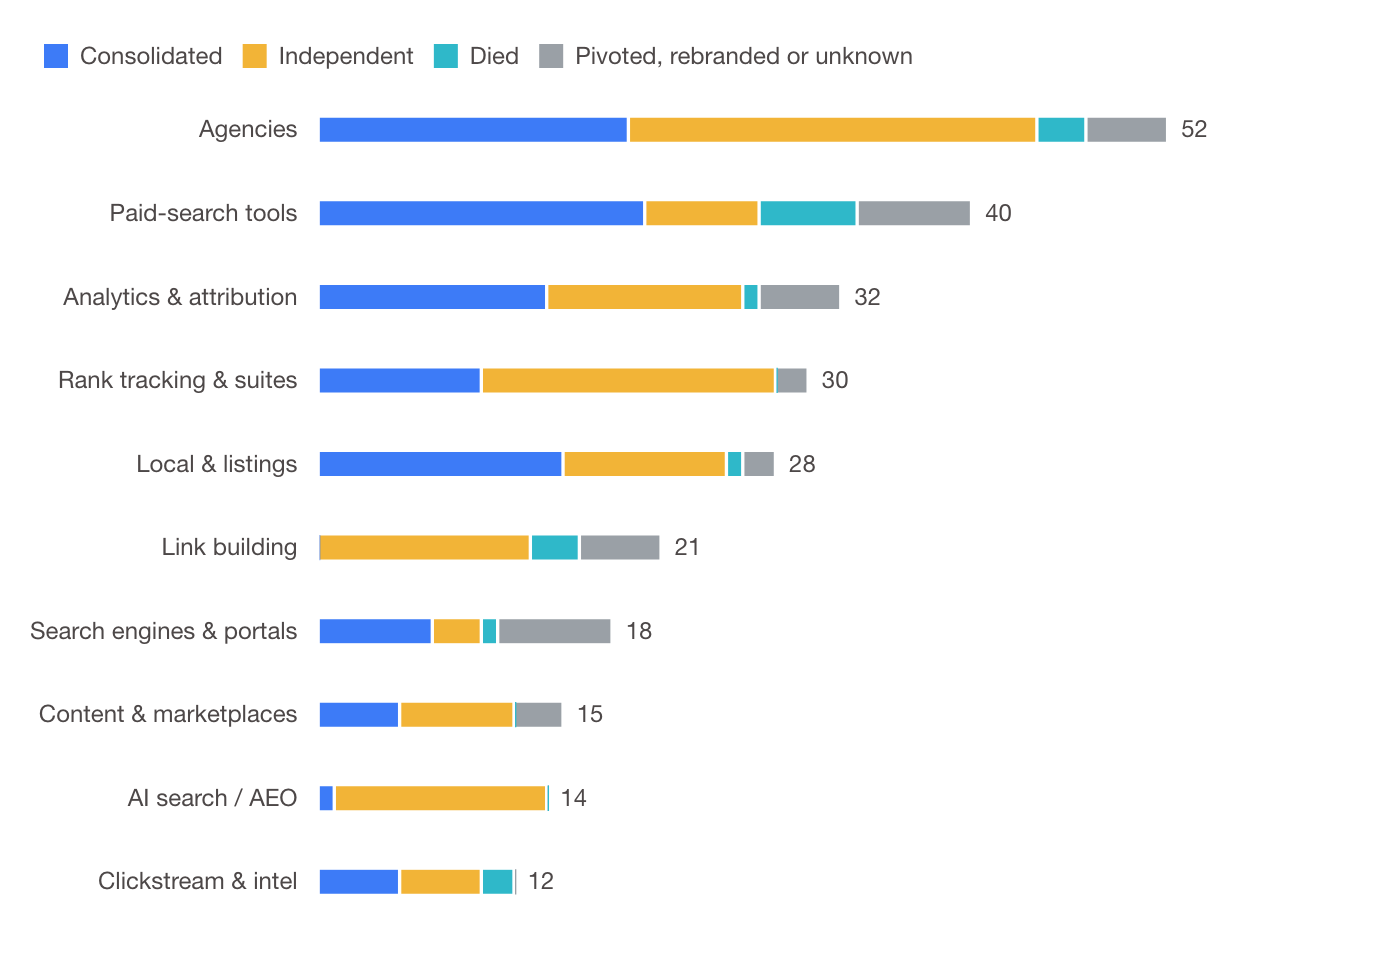
Paid-search tools are the cautionary tale: 40 traced, 7 still independent. Agencies and link builders, the people businesses, outlast the software.
How long until the exit
Years from first sponsorship to acquisition, merger, shutdown or pivot; 124 exits
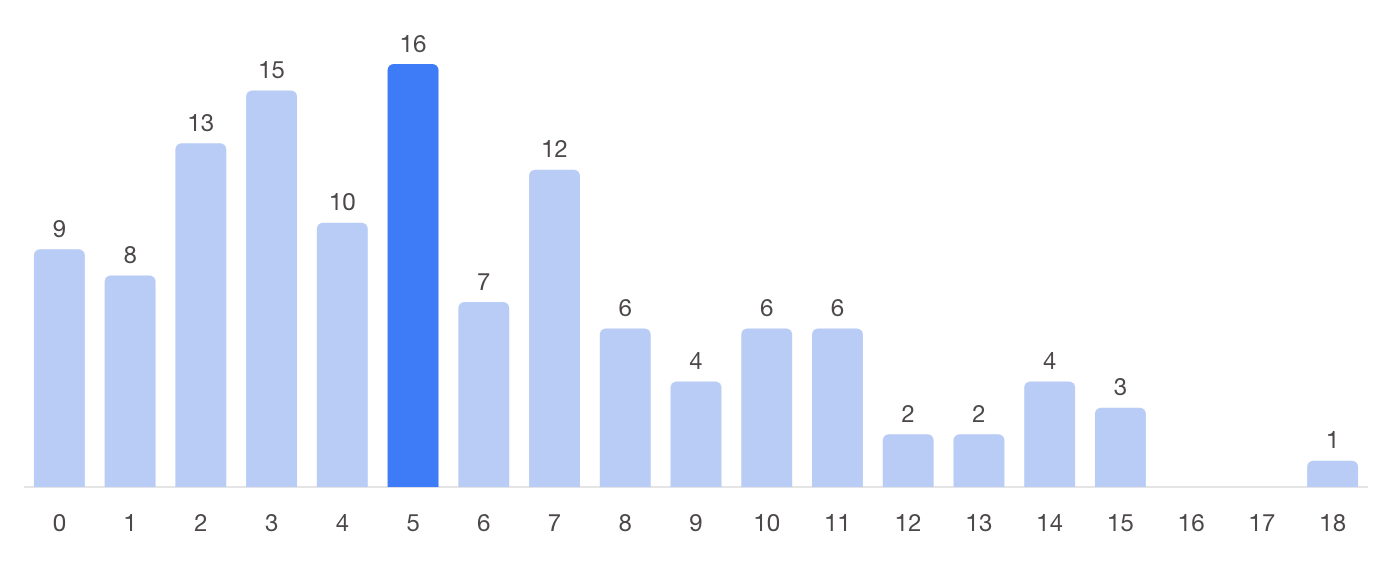
The median is 5 years. For shutdowns it is 6 years from first booth to death, and 4 years from last booth to death. The booth goes dark first.
- Crowded tool categories consolidate in 4–7 years. Paid-search tools had a median exit of 4 years; rank tracking and suites, 7.5.
- Buyers are platforms and roll-ups: Adobe (Omniture, Efficient Frontier, Semrush), Google (DoubleClick), Similarweb (The Search Monitor), Alpine/Traject (AuthorityLabs, SERPs, GatherUp), Conductor (Searchmetrics), BrightEdge (Oncrawl).
- Tools built on a loophole die; services built on relationships survive. 13 of 21 link builders are independent, while paid-link marketplaces and penalty-cleanup tools are gone.
- Measurement is always unsolved and always bought. Web analytics was rolled up (IndexTools, ClickTracks, WebSideStory), attribution was bought (Bizible, ClearSaleing, OptiMine), and clickstream died of privacy (Jumpshot) or competition (Compete).
- Incumbents rename the old product for the new channel. Listings, rank tracking and PPC vendors now sell AI visibility on the same booths.
Predictions for AEO
The short version
Most 2025–26 AEO tool sponsors will be acquired or gone by about 2030. The ones that remain will be inside suites. The people skills will outlast all of them.
AEO and prompt-tracking tools
Today 13 of the 14 AI search vendors I traced are independent, and AI-named sponsors went from 1 in 2022 to 10 in 2025. That is the paid-search bid-tool curve from 2007–2010, and that category ended with 7 of 40 independent. Surfer already sold 2 years after its first sponsorship. Marin's lesson matters most here: the killer was not a rival startup but the platforms' own tools becoming good enough. If the AI assistants ship their own visibility reporting, trackers that only count mentions are in Marin's position.
Citation builders
Link building is the healthiest category in the data, with 13 of 21 independent, and its share of sponsor appearances rose from 2.5% to 11.9%. But the link sellers that scaled a loophole were penalized (Text Link Ads in 2007 and 2013, teliad in 2014), and the cleanup tools died when the penalty wave passed. Citation building that is really outreach and digital PR will survive. Paid placement dressed as citations is waiting for its Penguin.
Measurement and attribution
Every generation's measurement vendor got bought or died. The AI search attribution problem I wrote about (https://www.naturalstateai.com/ai-search-attribution-problem/) will follow the same path: point tools get absorbed by suites, and the problem stays unsolved. Watch the data source. Jumpshot died because its panel collected data people did not know they were giving. Any AI visibility metric built on scraped answers or opaque panels carries the same terms-of-service and privacy risk.
Agencies
Of 52 agencies traced, 25 are still independent and only 3 died; 19 were consolidated into networks or roll-ups, and that is still happening (Previsible bought Internet Marketing Ninjas in July 2025). Agencies outlast tools because they can change what they sell. Over time, expect AEO agencies to roll up rather than die off.
That is not what I see yet. Lots of agencies are spinning up to tackle AI search, very few differentiate themselves in any way, and I'm not seeing much acquisition in this space so far. This looks like the early, crowded phase before consolidation, and if the history above holds, the shops with nothing distinct to sell are the ones that get absorbed or fade.
Practitioners
Only 1.9% of first-era sponsors are still on the floor, yet the work they enabled still exists. Skills transfer between vendors; tool lock-in does not. That is why the junior AEO talent gap I wrote about (https://www.naturalstateai.com/junior-aeo-talent-senior-teams/) worries me more than any single vendor's fate.
What to do
- Treat AEO tools as 3–5 year rentals
The median exit is 5 years. Export your data on a schedule and put data portability in the contract. - Watch the booth, not the deck
Shutdowns came a median 4 years after a company's last sponsorship. A vendor dropping off the circuit is an early signal. - Ask every vendor what could kill them
Platform features, a lost data partner, a privacy rule or running out of money: those caused most of the 31 failures here. - Buy relationships, not loopholes
Fund citation work that would survive a manual review: real outreach, original data, digital PR. - Own a measurement baseline
Keep your own logs, referral tracking and prompt samples so a vendor exit does not erase your history. - Invest in people
Train juniors on fundamentals that transfer: retrieval, entities, content quality, analytics.
Sponsor explorer
| Company | Category | Years | Booths | Outcome | Source |
|---|---|---|---|---|---|
| Microsoft (Bing / Microsoft Advertising) | search engines & portals | 2006–26 | 87 | public/IPO | about.ads.microsoft.com |
| Bruce Clay, Inc. | agencies | 2006–25 | 68 | independent | bruceclay.com |
| Marin Software | paid search tools | 2007–20 | 60 | shut down | businesswire.com |
| search engines & portals | 2006–24 | 59 | public/IPO | abc.xyz | |
| Moz | rank tracking & SEO suites | 2008–26 | 55 | acquired | geekwire.com |
| Majestic | directories & link building | 2011–26 | 51 | independent | majestic.com |
| Brafton | content farms & marketplaces | 2008–16 | 47 | independent | brafton.com |
| PRWeb | PR & press releases | 2006–14 | 46 | acquired | en.wikipedia.org |
| Acquisio | paid search tools | 2007–19 | 45 | acquired | globenewswire.com |
| Page One Power | directories & link building | 2011–25 | 44 | independent | pageonepower.com |
| Semrush | rank tracking & SEO suites | 2011–26 | 37 | acquired | businesswire.com |
| Searchmetrics | rank tracking & SEO suites | 2009–21 | 36 | acquired | globenewswire.com |
| TopRank Marketing | agencies | 2007–14 | 33 | independent | toprankmarketing.com |
| TopSEOs | training & events | 2010–20 | 33 | unknown | topseos.com |
| iProspect | agencies | 2006–13 | 32 | merged | en.wikipedia.org |
| seoClarity | rank tracking & SEO suites | 2010–26 | 32 | independent | seoclarity.net |
| Stone Temple Consulting | agencies | 2012–19 | 31 | acquired | perficient.com |
| Yahoo | search engines & portals | 2006–15 | 30 | acquired | en.wikipedia.org |
| BKA Content | content farms & marketplaces | 2012–23 | 29 | independent | bkacontent.com |
| Conductor | rank tracking & SEO suites | 2011–26 | 29 | independent | conductor.com |
| Marchex | analytics, attribution & call tracking | 2006–17 | 29 | public/IPO | marchex.com |
| Internet Marketing Ninjas | agencies | 2011–25 | 25 | acquired | searchengineland.com |
| STAT Search Analytics | rank tracking & SEO suites | 2012–26 | 25 | acquired | getstat.com |
| Textbroker | content farms & marketplaces | 2008–24 | 25 | independent | textbroker.com |
| Yext | local & listings | 2013–26 | 25 | public/IPO | investors.yext.com |
These are the 319 companies with traced outcomes, sorted by number of sponsor appearances. All 1,317 companies and every appearance with its archived source are in the dataset files (sponsors.csv, appearances.csv).
Methodology and caveats
- Survivorship bias: the 319 traced companies average 9.2 appearances each, against 3.4 across all companies. The 998 untraced companies are mostly one-year sponsors, where failures concentrate, so 20 shutdowns is a floor, not a rate.
- Independent means still operating, not thriving. Acquired includes rescues and fire sales; low prices are noted in the dataset rather than counted as failures.
- The 2023–26 cohort has had at most three years to fail; its 92% independence says nothing yet.
- Archive gaps: BrightonSEO 2021 pages were image-only, some SES and Pubcon years are thin, 2020–22 had few in-person events, and 2026 is partial.
- Category mix uses traced companies only, which cover 51–78% of appearances per year (about 52% since 2023).
- Failure causes are the primary cause the cited source gives; most failures had more than one.
- Disclosure: I work at AirOps, which appears in this data as a 2025–26 sponsor.
Sources
- BrightonSEO 2026 takeaways (naturalstateai.com)
- AI citation decay (naturalstateai.com)
- The AI search attribution problem (naturalstateai.com)
- Junior AEO talent and senior teams (naturalstateai.com)
- Reddit, YouTube and AI search strategy (naturalstateai.com)
- Marin Software goes bankrupt (sfgate.com)
- Local Corporation 10-K (2014) (sec.gov)
- Connexity buys Become (techcrunch.com)
- RIP Klout (techcrunch.com)
- Trada shuts down (bizwest.com)
- comScore sunsets Compete PRO (martech.org)
- Chitika shuts down (ppc.land)
- Datorama has joined the Salesforce family (salesforce.com)
- Previsible acquires Internet Marketing Ninjas (searchengineland.com)
Leave a Reply